
Student Loan Payoff Calculator
Pay Off Your Student Loans Faster
See how small extra payments can save you thousands in interest and shave years off your student loan repayment.

Student Loan Payoff Calculator
See how small extra payments can save you thousands in interest and shave years off your student loan repayment.
Add extra to save on interest and time.
National Statistics
Key data indicators relevant to the Student Loan Payoff Calculator for National.
How to Use theStudent Loan Payoff Calculator
A comprehensive walkthrough on how to maximize your savings using the free Student Loan Payoff Calculator provided by iCreditCalculators. Step-by-step tutorial.
About the Student Loan Payoff Calculator
The Student Loan Payoff Calculator with Extra Payments is a powerful tool designed to help borrowers visualize the impact of making additional payments towards their student loan principal.
Student loans can be a significant financial burden, often lingering for decades. However, even small extra contributions can have a dramatic compounding effect, reducing both the total interest paid and the time to be debt-free.
This calculator provides a clear "Before vs. After" comparison, showing you exactly how much money and time you can save by increasing your monthly monthly payment.
Features of the Student Loan Payoff Calculator
Interest Savings
Instantly see the dollar amount of interest saved by paying extra.
Payoff Timeline
Visualize your new debt-free date compared to the standard term.
Amortization Analysis
Understand how your payments are split between principal and interest.
Mobile Friendly
Calculate on the go with our fully responsive design.
Secure & Private
All calculations happen in your browser. No data is stored.
Instant Report
Get a detailed breakdown of your payoff strategy immediately.
How does the Calculator Work?
Calculation Process
Enter Loan Details
Input your current loan balance, interest rate, and remaining term.
Add Extra Payment
Enter an amount you can afford to pay extra each month.
See Savings
The calculator instantly projects your new payoff date and total savings.
Why should you use our Calculator?
| Feature | Our Calculator | Others |
|---|---|---|
| Accuracy | Math-Verified | Estimates |
| Visualization | Interactive Charts | Text Only |
| Simplicity | Instant Results | Complex Forms |
| Cost | 100% Free | Fees / Signup |
| Privacy | Client-side Only | Data Collection |
| Accessibility | Mobile Ready | Desktop Only |
| Speed | Real-time | Loading... |
| Context | Comprehensive Guide | Bare Tool |
| Support | FAQ Included | No Help |
| Updates | Regularly Maintained | Outdated |
10 Scenarios: What is the Use of This Calculator Online?
Student Loan Payoff Calculator Scenarios
| Scenario | Action Taken | Impact | Result |
|---|---|---|---|
| Aggressive Repayment | Double Monthly Payment | High | Halves Payoff Time |
| Modest Extra | +$50/month | Medium | Saves Thousands |
| Windfall Payment | One-time lump sum | High | Lowers Principal Fast |
| Bi-weekly Payments | Pay every 2 weeks | Medium | 1 Extra Payment/Year |
| High Interest Focus | Target highest APR | High | Max Interest Saved |
| Refinancing | Lower Rate + Same Payment | High | Faster Payoff |
| Income Increase | 50% of raise to debt | High | Accelerated Freedom |
| Debt Consolidation | Combine Loans | Low | Simplified Bills |
| Minimum Only | No Extra Payment | Negative | Max Interest Paid |
| Variable Income | Pay Extra When Able | Medium | Flexible Savings |
Case Studies: Real World Success Stories
Recent Graduate
Situation
$30k debt, 10-year term.
Outcome
Paid +$100/mo extra.
Mid-Career Professional
Situation
High interest private loans.
Outcome
Refinanced & paid extra.
Medical Resident
Situation
$200k med school debt.
Outcome
Paid interest during residency.
Public Servant
Situation
Eligible for PSLF.
Outcome
Prioritized PSLF over extra payments.
Parent PLUS Borrower
Situation
High rate parent loans.
Outcome
Refinanced to lower rate.
High Income Earner
Situation
Bonus allocated to debt.
Outcome
Lump sum payments annually.
Advantages and Risks
Advantages
- Reduces total interest paid over the life of the loan.
- Shortens the repayment period significantly.
- Improves debt-to-income ratio faster.
Disadvantages & Risks
- Reduces monthly cash flow available for other goals.
- Federal loans may have forgiveness options that extra payments negate.
- Opportunity cost of not investing that money elsewhere.
Risks & Mitigation Strategies
Comprehensive Guide to Student Loan Payoff Calculator
Comprehensive Guide to Student Loan Payoff
Paying off student loans is a marathon, not a sprint. However, you can change the pace. This guide explores the strategies for efficient repayment.
The Power of Extra Payments
Every dollar you pay above the minimum payment goes directly to reducing your principal balance (after outstanding interest is covered). A lower principal means less interest accrues in the following month, creating a snowball effect of savings.
Strategies for Success
- The Avalanche Method: Focus extra payments on the loan with the highest interest rate first.
- The Snowball Method: Focus on the smallest balance first for psychological wins.
- Bi-weekly Payments: Making half a payment every two weeks results in one full extra payment per year effortlessly.
Frequently Asked Questions
Was this Student Loan Payoff Calculator helpful?
Your feedback helps us improve our free tools.
Research & Development Support By: Vijayalaxmi Umachagi
CA, Legal, Financial Expert & Co-Founder
Vijayalaxmi Umachagi is a CA practitioner and financial expert by passion and an entrepreneur. She has 10+ years of Commerce, MCom and professional experience across finance and human resources who help developers build financial tools.
Built & Engineered By: Sachin Ramdurg
Software Engineer & Founder
Sachin Ramdurg is a software engineer by passion and an entrepreneur. He has 15+ years of engineering and professional experience across multiple domains, building accurate, high-performance financial tools and complex algorithms to make them accessible to everyone.
Community Insights
Real experiences and strategies from users of the Student Loan Payoff Calculator.
Share Your Insight
Priya
"I wish I found this tool sooner. The breakdown of {topic} is perfect."
Elena
"I'm usually terrible at math, but this made calculating my {topic} super simple."
Deep Dive: Student Loan Payoff Calculator Resources
Master your financial strategy with our expert-written, heavily researched guides.

What to Do Next?
Based on your analysis with the Student Loan Payoff Calculator, these tools will help you execute the next phase of your financial plan.
Student Loan Payoff Calculator From iCreditCalculators
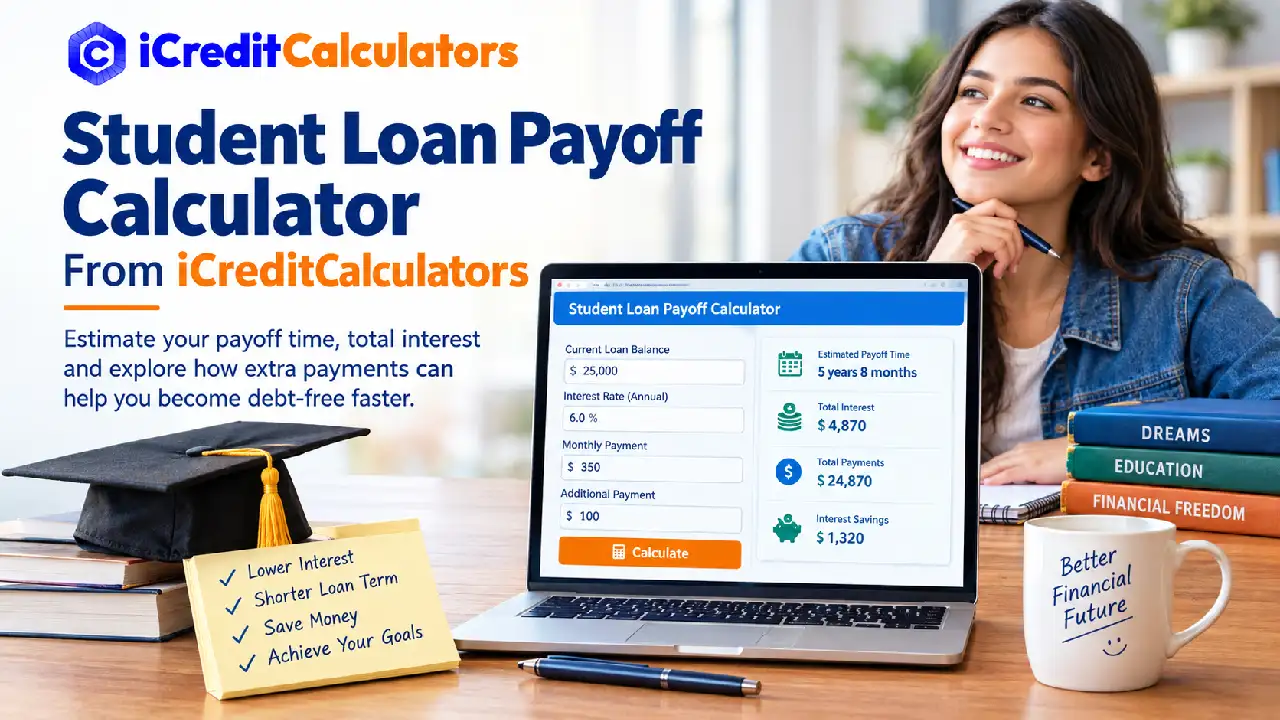
Student Loan Payoff Calculator From iCreditCalculators
Student loan debt can stay in your budget for years, especially when you only make the required monthly payment. If you want to understand how making additional payments towards your student loan principal can help, a student loan payoff calculator can show you the numbers clearly before you change your repayment strategy.
Instead of guessing how much interest you may pay or how many months remain, the calculator helps you estimate your payoff timeline, total interest, and the potential effect of paying extra toward your balance.
For many borrowers, the biggest question is not simply, “What is my monthly payment?” It is, “When will I actually be debt-free?”
That question matters because a student loan payment has two main financial effects. Part of the payment covers interest, while the rest reduces the principal balance. As the principal falls, future interest charges generally become smaller when the interest rate and repayment structure remain unchanged.
The Federal Student Aid Repayment Calculator also allows borrowers to compare repayment plans, estimated monthly payments, total amounts paid, principal, interest, and estimated payoff dates. However, a payoff-focused calculator serves a different purpose: it helps you look closely at the effect of your current payment and possible additional payments on the time and cost of repayment.
About the Student Loan Payoff Calculator
The Student Loan Payoff Calculator from iCreditCalculators is designed to help borrowers understand how long it may take to eliminate a student loan based on important loan details such as the outstanding balance, interest rate, current monthly payment, and additional payment amount.
The idea is simple.
You enter the numbers from your loan, and the calculator uses them to estimate your repayment path. You can then test different payment amounts and see how changing your monthly payment may affect the payoff period and total interest.
This is useful because a small additional payment can have a different effect depending on the loan balance, interest rate, and remaining repayment period.
For example, suppose two borrowers each have $30,000 of student debt. One borrower has a relatively low interest rate and the other has a higher rate. If both borrowers add $100 to their monthly payment, the savings will not necessarily be identical.
The calculator gives you a way to test those differences rather than relying on a general rule.
What Does the Calculator Help You Estimate?
Depending on the information entered, the calculator can help you understand:
- Estimated monthly payment
- Additional monthly payment
- Estimated payoff time
- Total amount paid
- Estimated total interest
- Potential interest savings
- Potential time saved
- Remaining balance over the repayment period
- The effect of changing your payment amount
The results are estimates rather than a promise of what your loan servicer will charge. Federal Student Aid similarly notes that calculator results are estimates and that final repayment terms are determined by the loan servicer after a repayment plan is processed.
What Is a Student Loan Payoff Calculator?
A student loan payoff calculator is a financial planning tool that estimates how quickly a borrower can repay a student loan under a selected payment strategy.
The calculation generally starts with the current principal balance and the interest rate. It then considers the regular payment and, when applicable, an additional payment toward the loan.
The calculator can simulate the balance month by month.
For example, imagine that your current student loan balance is $25,000 and your interest rate is 6%. If your required payment is $278 per month, you can enter that information and see the estimated repayment period.
You can then test a different payment, such as $350 per month.
The important question becomes:
How much sooner could the loan be paid off, and how much interest could potentially be avoided?
That comparison is often more useful than looking at the monthly payment alone.
A longer repayment period may reduce the required monthly payment, but it can also increase the amount of interest paid over time. The CFPB notes that extending a federal student loan repayment period can lower monthly payments while increasing total interest costs.
Why Student Loan Payoff Planning Matters
Student loan repayment is a long-term financial commitment. A payment that appears manageable today can still result in a substantial total repayment amount when spread over many years.
This is why borrowers should look beyond the monthly bill.
Consider a simple example.
You owe $40,000 at a 6% annual interest rate. If your repayment plan requires a fixed monthly payment, the loan balance does not decline by the full amount of each payment. Interest is calculated first, and the remaining portion reduces principal.
At the beginning of the loan, the interest portion can take up a larger share of the payment.
As the balance falls, more of the payment can go toward principal.
This is the basic idea behind an amortization schedule.
Understanding this pattern helps explain why additional principal payments can matter. If your loan allows you to make extra payments without a prepayment penalty, reducing principal earlier can reduce the balance on which future interest is calculated.
The CFPB states that borrowers can generally make additional student loan payments and that extra payments can help reduce the balance faster. It also advises borrowers to check with their servicer about how additional payments are applied.
Student Loan Payoff Calculator Formula
The calculator can use standard loan amortization mathematics to estimate a fixed monthly payment.
For a loan with a fixed interest rate and fixed repayment term, the basic payment formula is:
M = P × [r(1 + r)ⁿ] ÷ [(1 + r)ⁿ − 1]
Where:
| Abbreviation | Meaning |
|---|---|
| M | Monthly loan payment |
| P | Current loan principal balance |
| r | Monthly interest rate |
| n | Total number of monthly payments |
The monthly interest rate is calculated from the annual interest rate:
r = Annual Interest Rate ÷ 12
If the annual interest rate is 6%, the monthly rate is:
r = 0.06 ÷ 12 = 0.005
That represents a monthly rate of 0.5%.
How the Payoff Calculation Works
The calculator can then model each payment period.
For each month:
- Monthly interest is calculated from the current balance.
- The interest amount is deducted from the payment.
- The remaining payment reduces the principal.
- The new balance becomes the starting balance for the next month.
- The process continues until the balance reaches zero.
A simplified monthly calculation can be represented as:
Monthly Interest = Current Balance × Monthly Interest Rate
Then:
Principal Paid = Monthly Payment − Monthly Interest
And:
New Balance = Current Balance − Principal Paid
When an additional payment is included, that extra amount can be added to the regular payment for the payoff simulation, subject to how the borrower's loan servicer applies overpayments.
This is important because extra payment allocation matters. The CFPB explains that payments generally go first toward certain fees, then interest, and then principal. Borrowers who pay more than the required amount can request that excess amounts be applied toward principal.
How to Use the Student Loan Payoff Calculator
Using the calculator should be straightforward. Before entering the information, have your latest student loan statement available so you can use current figures.
Step 1: Enter Your Current Loan Balance
Enter the amount you currently owe.
Do not automatically enter the original amount you borrowed unless it is still your current balance.
For example:
- Original student loan: $35,000
- Current balance: $27,400
The calculator should generally be based on the current balance when you are analyzing an existing loan payoff.
Step 2: Enter the Interest Rate
Enter your current annual interest rate.
For example:
- Loan balance: $27,400
- Annual interest rate: 5.5%
If you have multiple loans with different interest rates, consider analyzing each loan separately or using the appropriate combined inputs supported by the calculator.
Step 3: Enter Your Current Monthly Payment
Enter the amount you currently pay each month.
For example:
- Current monthly payment: $300
This gives the calculator a starting point for estimating your repayment timeline.
Step 4: Enter an Additional Payment
If you are considering paying more than your required payment, enter the extra amount you are considering.
For example:
- Regular payment: $300
- Additional payment: $100
- Total modeled payment: $400
This allows you to compare the current strategy with the accelerated strategy.
Step 5: Calculate Your Results
Click the calculate button to generate the estimated payoff information.
Review the estimated:
- Payoff period
- Total interest
- Total payments
- Interest savings
- Time saved
Do not focus on only one number.
A payment that saves a large amount of interest may require a monthly amount that is difficult to maintain. Your goal should be to understand the trade-off between monthly cash flow and long-term borrowing cost.
How the Student Loan Payoff Calculator Works
The calculator works by modeling the loan balance over time.
Imagine that you have a $20,000 student loan at 5% annual interest.
The annual rate is converted into a monthly rate:
5% ÷ 12 = 0.4167% per month
The calculator then estimates the interest for the current month.
If the balance were exactly $20,000, the approximate first month's interest under a simple monthly-rate assumption would be:
$20,000 × 0.004167 ≈ $83.34
If your monthly payment were $250, approximately $83.34 would represent that month's interest, while roughly:
$250 − $83.34 = $166.66
would go toward principal under this simplified example.
The following month, interest would be calculated on the new balance rather than the original $20,000.
That is why reducing the principal earlier can change the future repayment path.
Why Extra Payments Can Change the Timeline
Suppose your normal payment is $250.
Now imagine you increase it to $300.
That additional $50 does not look dramatic by itself. But if it is consistently applied to the loan balance, the effect can accumulate over many months.
You are not simply paying $50 more today.
You are potentially reducing the balance that future interest calculations are based on.
Federal Student Aid currently advises borrowers that paying a little extra each month can reduce interest and total loan cost over time.
However, borrowers should check their specific loan terms and servicer instructions before assuming every extra dollar will be handled exactly as expected.
A Simple Student Loan Payoff Example
Consider this hypothetical borrower:
- Current balance: $30,000
- Interest rate: 6%
- Regular monthly payment: $333
- Additional monthly payment: $67
- Total modeled monthly payment: $400
The borrower can compare two scenarios:
Scenario A: Continue paying $333 per month.
Scenario B: Pay $400 per month.
The second scenario requires an additional $67 every month, but the higher payment can reduce the principal faster.
The exact payoff period and interest savings depend on the starting balance, rate, payment structure, and how the servicer applies additional payments.
This is where the calculator becomes useful. Instead of assuming that an extra payment will save a particular amount, you can enter your actual numbers and compare the resulting estimates.
Student Loan Repayment in the Current U.S. Environment
Federal student loan repayment rules and available repayment plans can change, so borrowers should not rely on old calculator articles or outdated repayment assumptions.
As of 2026, Federal Student Aid provides a Repayment Calculator that lets borrowers review eligible repayment plans, estimated monthly payments, total amounts paid, principal and interest, and estimated end-of-term dates. The agency also notes that eligibility can depend on factors such as the type of federal loan and when the loan was first disbursed.
This distinction matters.
A payoff calculator helps answer questions such as:
- How quickly could I repay this balance?
- What happens if I pay an extra $50?
- What happens if I pay an extra $100?
- How much interest might I save?
A repayment-plan calculator is more focused on comparing eligible repayment plans and their estimated payment structures.
Both can be useful, but they answer different questions.
What You Should Check Before Making Extra Payments
Before changing your student loan payment strategy, check your loan account and repayment terms.
Pay particular attention to:
- Current outstanding principal
- Current interest rate
- Monthly payment
- Loan type
- Repayment plan
- Outstanding accrued interest
- Whether you have multiple loans
- How your servicer applies additional payments
- Whether you are pursuing loan forgiveness or another federal benefit
The CFPB specifically recommends contacting your servicer when making extra payments so you understand how the additional amount will be applied.
This can be especially important if you are pursuing a forgiveness program. Paying a loan down faster may not always produce the same financial outcome as following a strategy designed around qualifying payments and potential forgiveness.
That is why the calculator should be treated as a planning tool, not as a replacement for reviewing your actual loan terms.
Key Takeaways So For
- A student loan payoff calculator estimates how long it may take to repay your debt.
- The calculator can help estimate total interest and total repayment cost.
- Additional payments can potentially reduce the principal faster.
- Lower principal can reduce future interest under a standard amortizing loan structure.
- Your current balance, rather than only your original loan amount, is important when calculating an existing loan payoff.
- The annual interest rate must be converted into a monthly rate when using a monthly amortization formula.
- Extra payments should be checked with your loan servicer to make sure they are applied according to your intended strategy.
- Federal Student Aid's current repayment calculator and a payoff calculator serve related but different purposes.
- If you are pursuing forgiveness or an income-driven repayment strategy, consider the effect of extra payments before changing your approach.
- Use actual figures from your latest loan statement whenever possible.
The main value of the Student Loan Payoff Calculator from iCreditCalculators is that it turns an abstract repayment goal into numbers you can compare. Instead of simply knowing that you owe a certain amount, you can model what happens when you change the payment and see how that change may affect your path to becoming debt-free.
Features of the Student Loan Payoff Calculator
The Student Loan Payoff Calculator from iCreditCalculators is designed to make student loan repayment easier to understand. Instead of looking at a loan statement and seeing only the amount due, you can use the calculator to explore different repayment situations.
A useful calculator should help you answer practical questions. How long will my loan take to pay off? What happens if I pay more each month? How much interest could I avoid? Is the extra payment affordable for my budget?
These questions are more useful when you can see the numbers side by side.
1. Current Balance Calculation
The calculator starts with the amount you currently owe.
This is important because your current balance may be very different from the amount you originally borrowed. If you borrowed $40,000 several years ago and have already paid down $10,000 of principal, using $40,000 as your starting balance would not accurately represent your current payoff situation.
2. Interest Rate Input
The interest rate affects how quickly interest accumulates.
A loan with a higher interest rate generally costs more to carry when other factors are the same. This is why the interest rate should always be checked from your current loan information instead of using an assumed rate.
3. Monthly Payment Analysis
The calculator allows you to see how your regular monthly payment affects the payoff period.
This is useful when your payment is fixed and you want to know approximately how many payments remain.
4. Additional Payment Analysis
One of the most useful functions is testing an additional payment.
For example, you could compare:
- $350 per month
- $400 per month
- $450 per month
- $500 per month
The difference between these payment levels can help you understand how much additional cash flow would be required to accelerate repayment.
5. Estimated Interest Cost
The calculator can estimate how much interest may be paid over the modeled repayment period.
This gives you another way to look at your loan.
A $400 monthly payment does not mean that your total borrowing cost is simply $400 multiplied by the number of months. Interest is part of the total cost, and the amount depends on the balance, interest rate, repayment period, and payment structure.
6. Estimated Payoff Date
A payoff calculator can translate a number of remaining payments into an estimated timeframe.
That can make a long-term debt goal easier to understand.
Instead of saying, “I have a student loan,” you can work toward a specific target such as “I want this balance paid off within five years.”
7. Scenario Comparison
Scenario testing is particularly helpful.
You can calculate one situation using your current payment and then calculate another using a higher payment.
The difference between the two scenarios can show the potential value of accelerating repayment.
Why Additional Payments Can Make a Difference
Student loan interest is one reason repayment can take longer than borrowers expect.
When a payment is made, the money is generally applied to fees first, then interest, and then principal. The CFPB explains that borrowers who pay more than the required amount can request that excess money be applied toward principal. Reducing principal can lower the overall cost of the loan and help the borrower become debt-free faster.
Consider a borrower with a $25,000 balance.
If the borrower pays only the required amount, the loan follows its normal repayment schedule. If the borrower consistently adds $100 to the payment and that additional amount is properly applied to the balance, the principal can fall faster.
The effect can build over time.
However, borrowers should not assume that every extra payment automatically works in the same way. The CFPB warns that some servicers may place borrowers into “paid ahead” status, meaning an extra payment can be credited toward future scheduled payments rather than immediately producing the intended principal reduction.
This is why the calculator should be combined with careful account management.
How to Use Extra Payments Strategically
There are several ways to structure an additional payment.
You could add a fixed amount every month.
For example:
Regular Payment + Extra Payment = Total Monthly Payment
If your regular payment is $400 and your extra payment is $100:
$400 + $100 = $500
You could also make occasional lump-sum payments.
For example, you might receive a tax refund, work bonus, or other amount and decide to put part of it toward your student loan.
The calculator can help you compare the potential effect of different payment amounts, but your actual loan account should always be checked before making the payment.
Fixed Extra Payment Strategy
A fixed extra payment is simple to follow.
For example:
- Required payment: $350
- Extra payment: $75
- Total monthly payment: $425
This approach can work well for someone whose monthly income is stable.
The main advantage is consistency. Instead of waiting until the end of the year to make a large payment, the borrower gradually reduces the balance throughout the year.
Occasional Lump-Sum Strategy
A borrower may not have enough monthly cash flow to increase every payment.
Instead, the borrower could make occasional additional payments.
For example:
- Regular payment: $350
- Monthly extra: $0
- Annual additional payment: $1,000
The financial effect can differ from adding $83.33 every month because the timing of principal reduction matters.
The calculator can be used to compare these approaches when its inputs support the relevant payment structure.
Percentage-Based Strategy
Another approach is to dedicate a percentage of extra income to the loan.
For example, someone might decide to put 25% of an annual bonus toward student debt.
This can make the strategy easier to maintain because the additional payment changes with the person's income rather than forcing a larger fixed payment every month.
Important Point About Loan Forgiveness
Paying a student loan faster is not automatically the right strategy for every borrower.
If you are pursuing a federal forgiveness program, the effect of making additional payments can be different from the situation of someone who simply wants to eliminate the debt as quickly as possible.
Federal Student Aid's current Repayment Calculator can compare repayment plans and can also model situations involving Public Service Loan Forgiveness. The current tool provides estimated total payments, principal and interest, potential discharge amounts, and estimated end dates based on the information entered.
Therefore, if forgiveness is part of your financial plan, compare the potential benefit of faster repayment with the rules of the program you are using.
Do not use a simple payoff calculation as the only basis for changing a federal repayment strategy.
Student Loan Payoff Calculator vs. Repayment Calculator
These two tools can sound similar, but they answer different questions.
A student loan payoff calculator is mainly concerned with eliminating the balance.
A federal repayment calculator can help you compare repayment plans, estimated monthly payments, total amounts paid, interest, discharge amounts, and estimated end dates.
| Tool Purpose | Main Question |
|---|---|
| Student Loan Payoff Calculator | How quickly can I repay the loan? |
| Additional Payment Calculator | What happens if I pay extra? |
| Federal Repayment Calculator | Which eligible repayment options can I compare? |
| Amortization Calculator | How is each payment divided between interest and principal? |
Using the right calculator for the right question can prevent confusion.
Five Factors That Affect Your Student Loan Payoff
1. Starting Balance
A larger balance generally requires more money to repay when the interest rate and other terms are the same.
2. Interest Rate
A higher rate generally increases the interest cost of carrying the same balance.
3. Monthly Payment
A larger payment generally reduces the balance faster when the additional amount is actually applied toward the loan.
4. Additional Payments
Extra payments can accelerate repayment when they reduce principal rather than simply advancing the next due date.
5. Repayment Structure
Your actual repayment plan matters.
Federal student loan repayment options have changed in 2026. Federal Student Aid currently lists fixed-payment options as well as income-based options, and it states that the repayment plans available to a borrower depend on factors such as loan type and when the loans were first disbursed.
That is why a calculator result should always be interpreted in the context of your actual loan.
10 Student Loan Payoff Calculator Examples
The following examples show how borrowers can use the calculator to understand different repayment situations. These are hypothetical examples, not quotes from a lender or predictions of an individual borrower's actual account.
The calculations use simplified fixed-rate amortization assumptions where applicable. Actual student loan interest calculations can differ depending on loan type, servicer practices, payment dates, accrued interest, capitalization, and repayment plan.
Example 1: $20,000 Student Loan With No Extra Payment
Suppose a borrower has:
- Current balance: $20,000
- Annual interest rate: 5%
- Monthly payment: $212
- Additional payment: $0
Using the standard amortization formula:
M = P × [r(1 + r)ⁿ] ÷ [(1 + r)ⁿ − 1]
the borrower can estimate the payment needed to repay the balance over a selected fixed term.
For a 10-year example:
P = $20,000
r = 0.05 ÷ 12 = 0.004167
n = 120 months
The calculated payment is approximately:
M ≈ $212.13
So the borrower would pay approximately:
$212.13 × 120 = $25,455.60
The estimated interest would therefore be approximately:
$25,455.60 − $20,000 = $5,455.60
This example shows why the monthly payment alone does not tell the full story.
A borrower seeing a $212 payment may think the loan costs $212 each month. Over the full modeled term, however, the borrower pays substantially more than the original $20,000 because of interest.
Example 2: Adding $50 to a $20,000 Loan Payment
Now consider the same hypothetical $20,000 loan at 5%, but suppose the borrower pays $262 instead of approximately $212 each month.
The extra amount is:
$262 − $212.13 = $49.87
The borrower is putting about $50 more toward the loan each month.
Using the same fixed-rate assumptions, the higher payment can shorten the modeled repayment period and reduce total interest.
The exact result depends on the payment timing and loan calculation method, but the principle is straightforward: the higher payment reduces principal faster, leaving a smaller balance for future interest calculations.
This example is useful because $50 may appear small when viewed as a single monthly amount.
Over 12 months, however:
$50 × 12 = $600
That represents approximately $600 of additional annual payment.
If the borrower can maintain the higher payment without damaging their emergency savings or other financial priorities, the calculator can show the estimated long-term effect.
Example 3: $30,000 Balance With a $100 Extra Payment
Consider a borrower with:
- Balance: $30,000
- Interest rate: 6%
- Current payment: $333
- Extra payment: $100
- Total modeled payment: $433
The borrower is considering whether an extra $100 per month is worthwhile.
The annual additional payment would be:
$100 × 12 = $1,200
That is $1,200 more directed toward the debt over a full year.
At a 6% annual rate, the starting monthly rate under a simplified monthly calculation is:
0.06 ÷ 12 = 0.005
The first month's interest on a $30,000 balance would be approximately:
$30,000 × 0.005 = $150
If the borrower pays $433, the simplified first-month principal reduction would be:
$433 − $150 = $283
The following month's interest would then be based on the lower balance, assuming the same calculation method and no other changes.
The key point is not the first month's savings alone.
The advantage of additional principal reduction can continue throughout the repayment period because each subsequent interest calculation begins with a different balance.
Example 4: $40,000 Loan With Two Payment Strategies
Suppose a borrower owes $40,000 at a 6.5% annual interest rate.
The borrower has two choices for comparison:
Strategy A
Monthly payment = $450
Strategy B
Monthly payment = $600
The second strategy requires:
$600 − $450 = $150
more every month.
Over one year, the additional payment equals:
$150 × 12 = $1,800
The calculator can model both strategies and display their estimated payoff periods and interest costs.
This gives the borrower a practical comparison.
Instead of asking, “Should I pay more?” the borrower can ask a more useful question:
“Can my budget comfortably support the extra $150, and what does the calculator show that extra payment could change?”
That is a better way to use a payoff calculator because it combines the mathematical result with real household cash flow.
A borrower should still maintain an appropriate emergency reserve and account for other high-priority financial obligations before committing to a higher monthly debt payment.
Example 5: $50,000 Loan With a $200 Additional Payment
Now consider a larger balance:
- Current balance: $50,000
- Annual interest rate: 6%
- Existing payment: $550
- Additional payment: $200
- Total modeled payment: $750
The borrower is considering a $200 monthly increase.
Over one year:
$200 × 12 = $2,400
of additional payments could be made.
At a 6% annual rate, the simplified monthly interest rate is:
0.06 ÷ 12 = 0.005
The approximate first month's interest on $50,000 would be:
$50,000 × 0.005 = $250
Under the simplified calculation, a $750 payment would leave:
$750 − $250 = $500
for principal reduction during that first month.
With a $550 payment, the corresponding first-month principal reduction would be approximately:
$550 − $250 = $300
The difference is:
$500 − $300 = $200
That is exactly the additional payment.
As the balance falls, the interest portion can also fall under a standard amortization structure. This illustrates why a borrower should look at the entire repayment path rather than focusing only on one month's interest.
What These Examples Tell You
These examples show an important feature of student loan repayment: payment size and timing matter.
An additional $50, $100, or $200 may seem small compared with a large student loan balance. But when repeated every month, those additional payments can become meaningful amounts over a year.
For example:
$50 × 12 = $600
$100 × 12 = $1,200
$200 × 12 = $2,400
That does not mean the entire amount becomes immediate interest savings. The additional money generally reduces the balance, while the interest savings arise from having a lower balance on which future interest can be calculated.
The actual savings depend on the loan's terms and payment application.
The CFPB specifically advises borrowers to understand how their servicer applies extra payments and notes that additional payments can help reduce the loan balance faster.
When Paying Extra May Need More Thought
Paying off student debt faster can be attractive, but the decision should fit your complete financial situation.
Before increasing your payment, consider whether you have:
- Emergency savings
- High-interest credit card debt
- Essential insurance coverage
- Retirement contributions
- Upcoming major expenses
- Other loans with higher interest rates
For example, suppose you have a student loan at 5% but a credit card balance at 24%.
Putting every available dollar toward the student loan may not be the only strategy worth considering. The interest rates and tax treatment of different debts can change the financial comparison.
Likewise, if you have no emergency savings, directing every extra dollar toward student debt could leave you financially vulnerable if an unexpected medical bill, car repair, or temporary loss of income occurs.
The calculator can show the mathematical effect of a larger payment, but it cannot decide whether that payment fits your overall financial plan.
How to Compare Your Current Payment With an Accelerated Payment
One of the easiest ways to use the calculator is to create two scenarios.
Scenario A: Current Payment
Enter:
- Current balance
- Interest rate
- Current monthly payment
- No additional payment
Record the estimated payoff period and total interest.
Scenario B: Accelerated Payment
Keep the same:
- Current balance
- Interest rate
Then increase the payment.
For example:
Current payment = $350
Accelerated payment = $450
Compare the two results.
Look at:
- Months saved
- Estimated interest reduction
- Additional monthly cash required
- Total amount paid
- Estimated payoff date
This side-by-side comparison gives you a clearer picture than looking at the extra payment by itself.
A Practical Rule for Testing Extra Payments
Do not start with an amount that makes your budget uncomfortable simply because the calculator shows a faster payoff.
Instead, test several realistic amounts.
For example:
| Scenario | Monthly Payment |
|---|---|
| Current | $350 |
| Option 1 | $375 |
| Option 2 | $400 |
| Option 3 | $450 |
| Option 4 | $500 |
Then compare the estimated results.
This approach lets you see how different payment levels change the loan.
The most useful payment is not necessarily the largest payment you can make for one month. A sustainable payment that you can maintain consistently can be more practical for long-term planning.
Keep Your Loan Records Updated
Your calculator result is only as useful as the information you enter.
Check your latest loan statement for:
- Current principal balance
- Interest rate
- Current payment
- Accrued interest
- Due date
- Loan type
- Repayment plan
Also check your servicer's records after making an additional payment.
The CFPB recommends keeping records of student loan transactions and communications with your servicer.
This is particularly useful if you are making repeated extra payments and want to confirm that the payments are being applied as intended.
A Note About Interest Capitalization
Interest capitalization can affect your starting balance and future interest costs.
Capitalization occurs when unpaid accrued interest is added to the principal balance. Once that happens, future interest can be calculated using the higher balance.
The CFPB explains that capitalization can occur in specific circumstances and that borrowers should understand when unpaid interest may be added to principal.
For this reason, do not assume that the balance shown on an old statement is still the balance you should use.
Use the most recent information available.
Key Takeaways So For
Before moving to the final section of the article, keep these points in mind:
- The calculator can be used to compare different payment scenarios.
- A larger payment can reduce principal faster when the extra amount is properly applied.
- Extra payments can potentially reduce the total interest cost.
- A $100 additional payment equals $1,200 per year if maintained for 12 months.
- Always check how your loan servicer applies additional payments.
- A payment credited toward future bills is not necessarily the same as a payment immediately reducing principal.
- Federal repayment plans and eligibility can change, so current federal guidance should be checked before changing a repayment strategy.
- Borrowers pursuing forgiveness should consider how extra payments could affect their broader repayment strategy.
- Use your current loan balance, not simply the amount you originally borrowed.
- Test several payment amounts instead of assuming that the largest possible payment is automatically the right choice.
- Keep records of your payments and communications with your servicer.
- Use the calculator as a planning tool and verify final loan terms with your servicer.
The biggest benefit of running several scenarios is that you can see the relationship between monthly cash flow, payoff time, and interest cost. That information gives you a clearer starting point for deciding how aggressively you want to repay your student loan.
Example 6: $15,000 Student Loan With a Higher Monthly Payment
Consider a borrower with:
- Current student loan balance: $15,000
- Annual interest rate: 5.5%
- Current monthly payment: $175
- Proposed payment: $225
The borrower wants to know whether increasing the payment by $50 is meaningful.
The additional payment is:
$225 − $175 = $50 per month
Over 12 months, that equals:
$50 × 12 = $600
The borrower is therefore considering putting an additional $600 toward the loan each year.
Under a simplified monthly interest calculation, the monthly rate is:
5.5% ÷ 12 = 0.004583
At the beginning of the example, approximate monthly interest would be:
$15,000 × 0.004583 ≈ $68.75
With a $175 payment, the simplified principal reduction would be approximately:
$175 − $68.75 = $106.25
With a $225 payment:
$225 − $68.75 = $156.25
The difference is $50.
As the balance declines, the interest portion can change. The calculator can model the full repayment path rather than looking at only the first month.
For a borrower who can comfortably afford the higher payment, comparing these two scenarios can make the long-term impact easier to understand.
Example 7: $25,000 Loan and a $1,000 Annual Lump-Sum Payment
Not every borrower can increase their monthly payment.
Suppose someone earns a yearly bonus and decides to make a $1,000 additional student loan payment.
The regular payment remains unchanged.
The repayment strategy is:
- Regular monthly payment: $300
- Additional annual payment: $1,000
- Interest rate: 5.5%
- Current balance: $25,000
The $1,000 payment is equivalent to:
$1,000 ÷ 12 = $83.33 per month
if it were spread evenly across a year.
However, the actual financial effect may not be identical because the timing of the payment matters.
If the $1,000 is paid earlier, the balance may be reduced sooner. A lower balance can mean less interest accrues afterward, depending on the loan's interest calculation method.
This is especially relevant for federal Direct Loans because Federal Student Aid states that Direct Loans accrue interest daily. The current Federal Student Aid guidance describes the daily-interest calculation as multiplying outstanding principal by the applicable interest-rate factor and the number of days since the last payment.
That means borrowers should not assume that dividing an annual lump sum into 12 equal payments will always produce exactly the same result as making the lump sum at one point during the year.
Example 8: Comparing $400 and $500 Monthly Payments
Suppose you have:
- Balance: $35,000
- Interest rate: 6%
- Current payment: $400
- Alternative payment: $500
The difference is:
$500 − $400 = $100
Over a year:
$100 × 12 = $1,200
The calculator can model both payment amounts.
The $400 scenario represents the borrower's existing repayment approach.
The $500 scenario represents an accelerated strategy.
The important numbers to compare are:
| Measurement | $400 Payment | $500 Payment |
|---|---|---|
| Monthly payment | $400 | $500 |
| Additional monthly amount | — | $100 |
| Additional annual amount | — | $1,200 |
| Estimated payoff period | Calculator result | Calculator result |
| Estimated total interest | Calculator result | Calculator result |
| Estimated total paid | Calculator result | Calculator result |
The purpose of this comparison is not to make the $500 payment look automatically better.
Instead, it shows the trade-off.
The borrower gives up $100 of monthly cash flow in exchange for potentially reaching the payoff point sooner and paying less interest over the modeled period.
That distinction is important when planning a real household budget.
Example 9: Multiple Student Loans With Different Interest Rates
Now consider a borrower who has three loans:
| Loan | Balance | Interest Rate |
|---|---|---|
| Loan A | $10,000 | 4.50% |
| Loan B | $15,000 | 6.50% |
| Loan C | $8,000 | 7.50% |
Total balance:
$10,000 + $15,000 + $8,000 = $33,000
The borrower has an additional $200 available each month.
One possible strategy is to direct additional money toward the loan with the highest interest rate, while continuing required payments on the others.
The highest rate in this example is Loan C at 7.5%.
The borrower should still verify the loan servicer's payment-allocation rules before assuming the additional amount will automatically be applied exactly as intended.
The CFPB advises borrowers who make additional payments to understand how their servicer applies the payment. It also notes that paying extra can help reduce the balance faster and lower the total cost of the loan.
For a borrower with multiple loans, a payoff calculator may therefore be more useful when each loan is examined individually rather than treating every balance as if it had the same interest rate.
Example 10: Choosing a Payment Based on a Five-Year Goal
Suppose a borrower has:
- Current balance: $28,000
- Interest rate: 6%
- Goal: Pay the loan off within five years
Five years equals:
5 × 12 = 60 months
The borrower can use the standard fixed-payment formula to estimate the monthly payment needed under a simplified amortization model:
M = P × [r(1 + r)ⁿ] ÷ [(1 + r)ⁿ − 1]
Where:
P = $28,000
r = 0.06 ÷ 12 = 0.005
n = 60
The resulting payment is approximately:
M ≈ $541.47
So, under these assumptions, a payment of roughly $541.47 per month would be needed to amortize $28,000 over 60 months.
The estimated total payments would be:
$541.47 × 60 ≈ $32,488.20
Estimated interest:
$32,488.20 − $28,000 ≈ $4,488.20
This example demonstrates another useful way to use a payoff calculator.
Instead of starting with a payment and asking, “When will I be done?” you can start with a target date and ask:
“What payment would I need to reach that goal?”
The actual payment required for a federal or private student loan can differ because real loans may use daily interest, different payment schedules, fees, accrued interest, or other terms. Federal Student Aid specifically explains that Direct Loans use daily interest calculations.
What Makes iCreditCalculators Useful for Student Loan Planning?
A student loan calculator should do more than produce a single number.
Its real value comes from helping borrowers understand the relationship between the variables.
A useful payoff calculation connects:
Balance → Interest → Payment → Principal Reduction → Payoff Time → Total Cost
Changing one input can change the rest of the calculation.
For example, increasing the interest rate increases the cost of carrying the balance. Increasing the payment can shorten the modeled repayment period. Increasing the repayment period can lower the required monthly payment but may increase total interest.
That makes scenario testing one of the most useful parts of the calculator.
Why Use the Student Loan Payoff Calculator From iCreditCalculators?
The calculator can be useful when you want a straightforward way to explore student debt without manually creating an amortization schedule.
It Helps Turn a Large Balance Into a Plan
Seeing a $30,000 or $50,000 student loan balance can feel difficult to interpret.
A calculator breaks that balance into measurable pieces.
You can see:
- Estimated monthly payment
- Estimated interest
- Estimated payoff time
- Additional payment amount
- Estimated interest savings
- Potential time savings
It Helps With “What If?” Questions
Financial decisions often involve uncertainty.
You may wonder:
What if I add $25?
What if I add $100?
What if I make one extra payment each year?
What if I want to pay the loan off in five years?
A calculator lets you test these questions using numbers.
It Can Help With Budget Planning
Suppose your current student loan payment is $350.
You may be considering increasing it to $425.
The difference is:
$425 − $350 = $75
That $75 should be evaluated against your monthly budget.
The calculator can tell you what the extra payment could do to the modeled loan timeline. Your budget tells you whether you can maintain that payment.
You need both pieces of information.
Why the Calculator Should Not Be Used Alone
A calculator gives you mathematical estimates.
It does not know every detail of your financial situation.
For example, it may not know:
- Whether you qualify for forgiveness
- Whether your income will change
- Whether your repayment plan will change
- Whether you have other higher-cost debt
- Whether your servicer will allocate an extra payment differently
- Whether you need to preserve cash for an emergency
- Whether tax rules affect your overall decision
Federal Student Aid's current Repayment Calculator is designed to help borrowers compare eligible federal repayment plans, including estimated monthly payments, total paid, principal, interest, discharge amounts, and estimated end-of-term dates. The agency emphasizes that these are estimates and that final terms are determined by the servicer after processing.
This is an important distinction.
The iCreditCalculators payoff calculator can help with payoff planning, while official federal tools should be used when you need to understand your current federal repayment-plan eligibility and terms.
Student Loan Payoff Calculator vs. Manual Calculation
You could create your own spreadsheet to calculate loan payments.
However, manually building a repayment schedule can become complicated when you need to account for:
- Changing balances
- Interest
- Payment dates
- Additional payments
- Different payment amounts
- Multiple loans
- Different interest rates
A calculator saves time and makes scenario testing easier.
A spreadsheet can still be useful for advanced personal budgeting, but a dedicated calculator is often a faster starting point.
Common Mistakes When Calculating Student Loan Payoff
Mistake 1: Using the Original Loan Amount
If your current balance is $22,000, do not enter $35,000 simply because that was the original amount borrowed.
Use the current balance when the calculator is designed to estimate the payoff of an existing loan.
Mistake 2: Ignoring the Interest Rate
A payment amount by itself does not tell you the cost of the loan.
Always include the applicable interest rate.
Federal Student Aid states that federal student loan rates depend on factors such as the loan type and first disbursement date. Current rates can therefore differ between borrowers.
Mistake 3: Assuming All Loans Calculate Interest the Same Way
A simple monthly amortization formula is useful for estimates, but not every student loan works exactly like a traditional fixed-payment mortgage.
For example, Federal Direct Loans accrue interest daily.
This is why the calculator result should be viewed as an estimate unless its inputs and calculation method exactly match the loan terms.
Mistake 4: Assuming Extra Payments Always Reduce Principal Immediately
This is a major point.
The CFPB warns that some servicers may place borrowers in paid-ahead status after an extra payment instead of immediately reducing the principal as the borrower expected.
Always check how your servicer handles overpayments.
Mistake 5: Ignoring Loan Forgiveness
If you are working toward a forgiveness program, aggressive payoff may change the economics of your repayment strategy.
Federal Student Aid's current Repayment Calculator specifically allows borrowers to explore repayment options with PSLF considerations.
Mistake 6: Making an Unsustainable Payment
A calculator can show that paying $800 per month would eliminate your loan faster.
That does not mean $800 is automatically affordable.
A repayment plan should fit your income, expenses, emergency savings, and other financial priorities.
Mistake 7: Forgetting to Update the Balance
Loan balances change.
If you made several payments since your last calculation, update the calculator with your latest information.
How to Create a Student Loan Payoff Plan
A practical payoff plan can be built in five stages.
Stage 1: Know Your Numbers
Collect:
- Current balance
- Interest rate
- Current payment
- Repayment plan
- Loan type
- Accrued interest
Stage 2: Set a Goal
Your goal might be:
- Reduce interest
- Pay off debt faster
- Reach a five-year payoff target
- Eliminate one loan first
- Become debt-free by a specific date
Stage 3: Test Multiple Payments
Run several scenarios.
For example:
$350 → $400 → $450 → $500
Record the payoff time and estimated total interest for each.
Stage 4: Check Your Budget
Do not select a payment simply because it produces the fastest mathematical result.
Make sure the payment is sustainable.
Stage 5: Monitor Your Actual Loan
After making payments, compare the calculator's estimate with your actual loan statement.
If there is a difference, investigate why.
The difference may result from payment timing, daily interest, accrued interest, fees, repayment-plan rules, or the way your servicer applies payments.
What About Current Federal Student Loan Changes?
Borrowers should pay particular attention to current federal repayment changes.
Federal Student Aid's August 2026 guidance says that repayment-plan eligibility depends on factors such as loan type and first disbursement date. It also says some plans, including PAYE and ICR, are scheduled to be retired no later than July 1, 2028.
Federal Student Aid's current repayment-plan information also reflects the introduction of the Repayment Assistance Plan (RAP) and Tiered Standard Plan beginning July 1, 2026.
This is one reason old student loan articles can become misleading.
A calculator article written several years ago may describe repayment options that are no longer available to every borrower.
For a current federal repayment decision, use the latest information available through StudentAid.gov and your loan servicer.
Student Loan Payoff Checklist
Before using the calculator, gather the following information:
- Current student loan balance
- Current interest rate
- Current monthly payment
- Loan type
- Repayment plan
- Accrued interest
- Number of loans
- Current income
- Monthly essential expenses
- Emergency savings
- Other outstanding debts
- Any forgiveness program you are pursuing
Then run the calculator using your current numbers.
Next, test at least two or three additional payment scenarios.
Finally, compare the results with your actual financial budget.
Frequently Asked Questions
What is a student loan payoff calculator?
A student loan payoff calculator is a tool that estimates how long it may take to repay a student loan and how much you may pay in interest based on inputs such as balance, interest rate, and payment amount.
It can also help you compare different payment strategies.
How does a student loan payoff calculator work?
The calculator uses the loan balance, interest rate, payment amount, and other applicable inputs to estimate how the balance changes over time.
For a standard fixed-rate amortization model, the payment formula is:
M = P × [r(1 + r)ⁿ] ÷ [(1 + r)ⁿ − 1]
The actual calculation can vary depending on the loan type and interest method.
Does paying extra on a student loan save money?
It can.
When an additional payment is applied toward principal, the loan balance can decline faster. A lower balance can reduce future interest under the applicable interest calculation method.
The CFPB confirms that paying more than the minimum can help borrowers reduce their loan balance faster.
How much extra should I pay toward my student loan?
There is no single extra payment that works for everyone.
You can use the calculator to test amounts such as $25, $50, $100, or $200 and then compare the results with your monthly budget.
The best amount to model is one you can reasonably maintain without neglecting other important financial needs.
Can I pay off my student loan early?
Generally, borrowers can make additional payments without a prepayment penalty, but you should check your specific loan and servicer instructions.
The CFPB states that borrowers can generally make additional student loan payments and recommends checking how those payments will be applied.
Should I make extra payments if I am pursuing student loan forgiveness?
You should analyze the situation before making a major change.
If you are pursuing forgiveness, making additional payments may affect the amount of debt remaining for potential discharge.
Federal Student Aid's current Repayment Calculator can be used to explore repayment options with PSLF considerations.
Does paying extra every month reduce interest?
If the extra payment reduces principal, it can reduce the balance on which future interest accrues.
However, the actual result depends on the loan's interest calculation and how the servicer applies the additional payment.
What happens if my student loan has a high interest rate?
A higher interest rate generally increases the cost of carrying the same balance.
You can use the calculator to compare how different payment amounts affect the estimated repayment period and total interest.
Is the student loan payoff calculator accurate?
It can provide a useful estimate when accurate loan information is entered.
However, calculator results are not necessarily identical to your servicer's actual payoff amount. Federal Student Aid also states that its own repayment calculator produces estimates and that final repayment terms are determined by the servicer.
Can I use the calculator for multiple student loans?
Yes, but multiple loans should be handled carefully because each loan can have a different balance, interest rate, repayment plan, and payment requirement.
For the clearest analysis, consider calculating each loan separately when appropriate.
What information do I need to calculate student loan payoff?
At minimum, you generally need:
- Current balance
- Interest rate
- Monthly payment
- Additional payment, if any
- Repayment term or target payoff period
For a real loan, also review the repayment plan and loan type.
What is the difference between principal and interest?
Principal is the amount of debt you owe.
Interest is the cost of borrowing that money.
As payments are made, part of the payment can cover interest while the remaining amount reduces principal, subject to the loan's terms and payment-allocation rules.
How can I pay off student loans faster?
Common approaches include:
- Increasing the regular payment
- Making additional principal payments
- Making occasional lump-sum payments
- Reviewing higher-interest loans first
- Avoiding unnecessary new debt
- Monitoring your balance regularly
Before changing your strategy, check whether you are pursuing forgiveness or another repayment benefit.
Should I pay student loans or invest extra money?
This is a personal financial decision.
The comparison may involve the student loan's interest rate, expected investment returns, taxes, risk, emergency savings, and other debts.
A payoff calculator can tell you what happens to the loan under different payment amounts, but it cannot determine the appropriate investment or debt strategy for your complete financial situation.
Does autopay lower student loan interest?
Federal Student Aid says borrowers with eligible Direct Loans can receive a 0.25 percentage-point interest-rate reduction for automatic debit payments.
Check your current loan terms and servicer information to confirm eligibility.
Can I make extra payments before my regular due date?
StudentAid.gov states that borrowers can make prepayments while in school or during a grace period, and additional payments can generally be made during repayment.
However, confirm how your servicer will apply the payment.
Why does my actual payoff amount differ from my calculator result?
Several factors can cause differences.
These can include:
- Daily interest accrual
- Payment timing
- Accrued interest
- Capitalized interest
- Fees
- Changes in repayment terms
- Payment allocation
- Rounding
- Different calculation methods
For federal Direct Loans, Federal Student Aid describes interest as accruing daily, which is one reason a simple monthly estimate may differ from an actual account balance.
Is a faster student loan payoff always better?
Not necessarily.
A faster payoff may reduce interest, but borrowers should also consider emergency savings, other debt, retirement contributions, forgiveness eligibility, and overall cash flow.
The calculator should help you understand the numbers so you can make a decision that fits your circumstances.
Final Thoughts on the Student Loan Payoff Calculator
Student loan repayment becomes easier to understand when you stop looking only at the monthly bill and start looking at the complete repayment picture.
Your current balance, interest rate, monthly payment, additional payment, repayment period, and loan terms all work together.
The Student Loan Payoff Calculator from iCreditCalculators gives you a simple way to test those variables and see how different payment strategies may affect your estimated payoff timeline and interest cost.
The most useful approach is to start with your real loan information.
Enter your current balance.
Enter your current interest rate.
Enter your existing payment.
Then test realistic additional payments.
For example, you might compare:
Current Payment → +$50→+$100 → +$200
The purpose is not to choose the biggest number simply because it produces the fastest payoff.
The purpose is to understand the trade-off between monthly affordability and long-term debt cost.
Remember that actual student loan calculations can differ from simplified calculator assumptions. Federal Direct Loans accrue interest daily, and your servicer's payment application can affect how extra payments change your balance.
Federal student loan borrowers should also consider their current repayment-plan eligibility and any forgiveness strategy before making a major repayment change. Federal Student Aid's current Repayment Calculator provides a separate way to compare eligible repayment plans and estimated total costs, and the agency notes that final terms are determined by the servicer.
The key is to use the calculator as a planning tool.
Know what you owe.
Understand how interest affects the balance.
Test different payment amounts.
Check how your servicer applies extra payments.
Consider your wider financial goals.
Then review the result against your actual loan statement.
Start Your Student Loan Payoff Calculation
If you are ready to understand your student loan payoff timeline, use the Student Loan Payoff Calculator from iCreditCalculators.
Enter your current loan details, test different payment amounts, and compare the estimated payoff time and interest cost.
A few minutes of calculation can give you a much clearer picture of what your student debt may look like months or years from now.
Know your numbers. Test your options. Build a repayment plan that fits your financial goals.
Sachin Ramdurg
Founder & Software Engineer
Sachin Ramdurg is the creator of iCreditCalculators.com. He brings over 15 years of software engineering expertise to build precision-engineered, privacy-first financial tools that empower consumers.